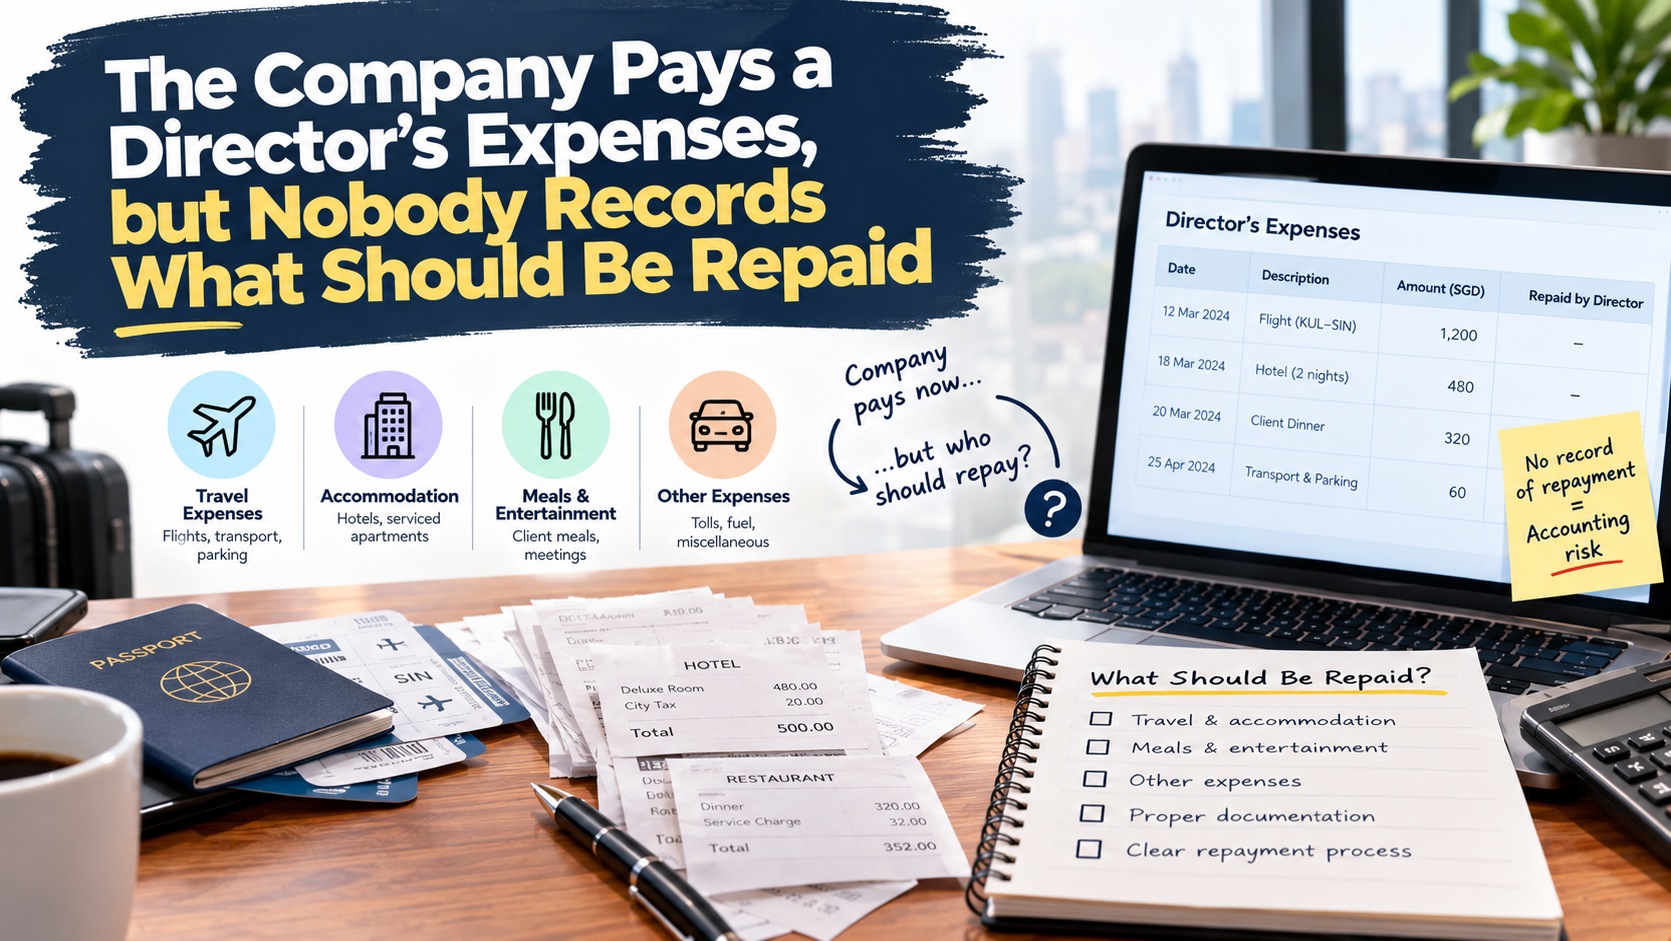
A director uses the company card during a business trip. The statement includes hotel accommodation, client meals and a few personal purchases. Finance records the payment under travel expenses, expecting the director to identify the private items later. That follow-up never happens.
Over time, similar transactions accumulate. Some are legitimate company costs, some may be approved remuneration or benefits, and others were meant to be repaid. The accounts no longer explain which is which. A balance described as “director’s account” may exist, but nobody can show how it was calculated or when it will be settled.
Gekonnt provides accounting services, including financial analysis and advisory support. For businesses dealing with mixed company and director expenditure, reliable reporting starts with identifying the purpose of each payment. The objective is to establish what the company should bear, what requires further review and what is genuinely recoverable from the director.
Start With the Transaction, Not the Card Used
A payment does not become a business expense simply because it was made using a company card. Equally, an expense paid personally by a director may belong to the company if the underlying facts support reimbursement.
Review what was purchased, who benefited and why the company incurred the cost. The bank or card statement establishes the payment, but supporting records explain its purpose. An invoice, receipt and brief business explanation often need to be considered together.
Avoid classifying transactions solely by merchant name. A hotel charge may cover a business stay, a personal extension or both. A restaurant receipt may relate to a client meeting, staff event or private meal.
The initial review should establish the facts without assuming misconduct or automatically accepting the expense. Clear evidence allows the company to reach a supported conclusion.
Separate Company Costs, Benefits and Repayable Amounts
Not every payment benefiting a director has the same treatment. A reimbursement for a genuine company purchase differs from an approved benefit provided under a remuneration arrangement. Both differ from a personal amount the director is required to repay.
Establish the relevant policy, agreement and approval. If a payment forms part of remuneration, it needs the appropriate treatment and reporting. If it is recoverable, the company needs a supported basis for recording that right and following up settlement.
Do not use a director receivable as a temporary destination for every unexplained item without further action. A ledger entry does not establish the terms, recoverability or permissibility of the arrangement.
Where the intended treatment is unclear, assign responsibility for resolving it promptly. Leaving the decision until year-end allows uncertainty to become a recurring feature of the accounts.
Review the Legal Position Before Treating Payments as Loans
An agreement that the director will repay later does not automatically make every arrangement permissible. Singapore’s Companies Act contains restrictions on certain loans, quasi-loans, credit transactions and related arrangements involving directors, with exceptions and conditions depending on the circumstances.
Paying an individual’s expenses on an understanding that they will reimburse the company may require consideration under those provisions. The analysis should reflect the company’s status and the actual arrangement, rather than the account name chosen by finance.
Obtain appropriate corporate or legal advice where necessary, particularly for recurring or substantial amounts. Recording a receivable is not a substitute for assessing whether the transaction should have been entered into.
This review is most useful before a pattern develops. A company should not treat informal repayment promises as a standing facility for personal expenditure without examining the implications.
Split Mixed Expenses Using Evidence
Mixed transactions need a reasonable, documented allocation. Ask for the underlying invoice and an explanation of the business and private elements. Where possible, identify separately charged items rather than applying an arbitrary percentage.
For example, a business trip may include additional hotel nights for a personal stay. The allocation should reflect the actual arrangement and relevant evidence. Different components, such as travel and accommodation, may need separate consideration.
Keep the calculation with the claim. A future reviewer should be able to understand the amount charged to the company and the amount assigned for repayment without asking the director to reconstruct the trip.
Where the information is incomplete, record the outstanding question and a deadline. Lack of documentation should trigger follow-up, not an automatic assumption that the entire amount is either deductible business expenditure or a recoverable personal balance.
A Practical Example of the Reconciliation
Consider a hypothetical company card statement totalling S$6,000. Supported review identifies S$4,800 of genuine company expenditure and S$1,200 of personal purchases that the director is required to repay. Assume the repayment arrangement has been appropriately reviewed and the receivable is supported.
The records should distinguish the S$4,800 company expenditure from the S$1,200 due from the director. Posting the entire S$6,000 as travel expense would conceal the repayment amount and misstate the classification.
If the director later repays S$700, the remaining balance is S$500. Match the receipt to the director’s account and preserve the supporting reference. The repayment is not new sales revenue.
This example excludes tax and is not a universal instruction for every director payment. The genuine company expenditure still needs classification by its nature, and any tax treatment requires separate consideration. The point is that the statement, review and settlement should form one traceable record.
Maintain an Individual Account for Each Director
Where amounts are owed by or to directors, keep the balances separately identifiable. Combining several people’s transactions into one account makes it difficult to establish responsibility or confirm the closing position.
The schedule should show the opening balance, individual transactions, approved adjustments, repayments and closing amount. Include dates, references and the reason for each movement.
Distinguish funds introduced by a director from expenses awaiting reimbursement and amounts owed to the company. A net balance can conceal significant transactions in both directions. Preserve the detail even where the eventual presentation is assessed separately.
Provide the director with a periodic statement and obtain clarification of differences. Agreement on the schedule is useful evidence, but it does not replace the underlying documents or the assessment of the transaction’s treatment.
Do Not Net Balances Without Reviewing the Basis
A company may owe a director reimbursement for one transaction while the director owes the company for another. It can be tempting to offset the amounts and clear the account immediately.
Before doing so, establish that the balances relate to the same parties and that the proposed settlement is properly supported and authorised. Retain the gross transaction detail and the documented basis for the offset.
Do not offset one director’s debt against money owed to another person simply because they are family members or shareholders. The individuals and legal rights remain distinct.
The same care applies across group companies. A payment made by one company cannot automatically be cleared against an amount owed by another without understanding and documenting the arrangement.
Keep Accounting and Tax Assessments Separate
Correct accounting classification does not automatically establish tax deductibility. IRAS guidance distinguishes allowable business expenses from private expenditure and other disallowed amounts. Some costs can have a business connection yet remain subject to specific restrictions.
Review the tax position using the nature of the payment and the relevant rules. Do not assume that an internal approval, a receipt or a director’s description of the expense settles the issue.
Where the company provides a benefit rather than requiring repayment, individual tax and employer reporting considerations may also arise. IRAS generally treats employment gains and benefits as taxable unless an exemption or administrative concession applies, but the treatment depends on the particular benefit and circumstances.
A bookkeeping adjustment alone may therefore be insufficient. Ensure the information reaches whoever prepares the relevant tax and remuneration reporting so the different records remain consistent.
Avoid Clearing the Balance Through an Unsupported Label
As year-end approaches, management may suggest transferring the outstanding amount to “director’s fees”, “bonus” or “dividends”. Those labels describe different transactions with their own requirements and consequences.
An amount should not be reclassified simply to remove an uncomfortable receivable. Establish whether there is a valid decision and supporting basis for the proposed treatment, with the appropriate corporate, accounting and tax review.
Do not backdate paperwork to suggest an arrangement existed when it did not. Retain the actual sequence of events and explain any correction or later decision.
Where an older entry was wrong, assess the error properly. The appropriate correction depends on the facts and significance, rather than a preference to keep the current year’s results unchanged.
Set Repayment Expectations and Follow Them Through
For supported repayable amounts, document the agreed timing and method of settlement. A vague statement that the director will repay “when convenient” provides little basis for cash planning or follow-up.
Track actual receipts against the agreement. If payment is delayed, obtain an explanation and reassess the position rather than automatically extending the date every month.
Review whether the receivable remains recoverable under the applicable accounting requirements. A director’s acknowledgement of the debt establishes useful information, but it does not guarantee payment.
Keep proposed payroll deductions or other recovery methods subject to the relevant contractual and legal requirements. Finance should not assume it can deduct any amount from any payment merely because the ledger shows a balance due.
Give Finance a Workable Approval Route
Finance staff may find it difficult to question expenditure incurred by a director. A clear policy reduces the need for personal negotiation by setting out the evidence, review and escalation process in advance.
Where practicable, arrange review by someone other than the person benefiting from the payment, with authority appropriate to the company’s structure. Smaller companies may need a proportionate process supported by external professional advice.
Define how missing receipts, mixed expenditure and exceptions are handled. The policy should apply consistently rather than change according to who used the card or requested reimbursement.
Make the approval record accessible to finance. A verbal discussion between directors does not help the accountant determine the entry unless the conclusion and relevant details are communicated.
Review the Balance as Part of the Monthly Close
Include director accounts in the regular reconciliation process. Match card statements, claims, bank transfers and repayments, and explain movements before the records become difficult to reconstruct.
Review outstanding items by original transaction date. Moving a balance between ledger accounts should not make it appear new or remove it from the follow-up schedule.
Gekonnt’s accounting services can support the consistent records needed for this review. Management supplies the commercial facts and approvals, while clear accounting schedules make the resulting balances easier to understand.
The monthly report should distinguish unresolved documentation from confirmed repayable amounts. This helps management focus on the action needed rather than treating every item as the same type of debt.
Prepare a Clear Record for Financial Reporting
At year-end, retain the reconciled schedules, supporting documents, approvals and evidence of subsequent repayments. Consider the applicable presentation and related-party disclosure requirements rather than assuming the account can be included within a general expense category.
Where the financial statements are audited, these records help explain the transactions and management’s assessments. They do not replace the auditor’s independent procedures or resolve legal questions about the arrangements.
Gekonnt’s financial statement audit offering connects to the need for supported reporting. A clear record allows significant balances to be examined without relying on an informal understanding between the owner and the bookkeeper.
The objective is not a zero balance at any cost. It is a balance that accurately reflects the facts, with appropriate treatment and evidence behind it.
Keep Company Spending Explainable
Director expenditure can become difficult to manage when business costs, benefits and personal payments share the same account without a clear review. The solution begins with evidence and a defined decision process.
Identify what each payment represents, assess any repayment arrangement appropriately and reconcile the movements regularly. Ensure accounting, corporate approvals and tax reporting reflect the supported position rather than a convenient label.
Speak with Gekonnt about its accounting and advisory support if director-related payments are making the accounts difficult to explain. Consistent records help the company understand what it should bear, what remains recoverable and which matters require further professional review.