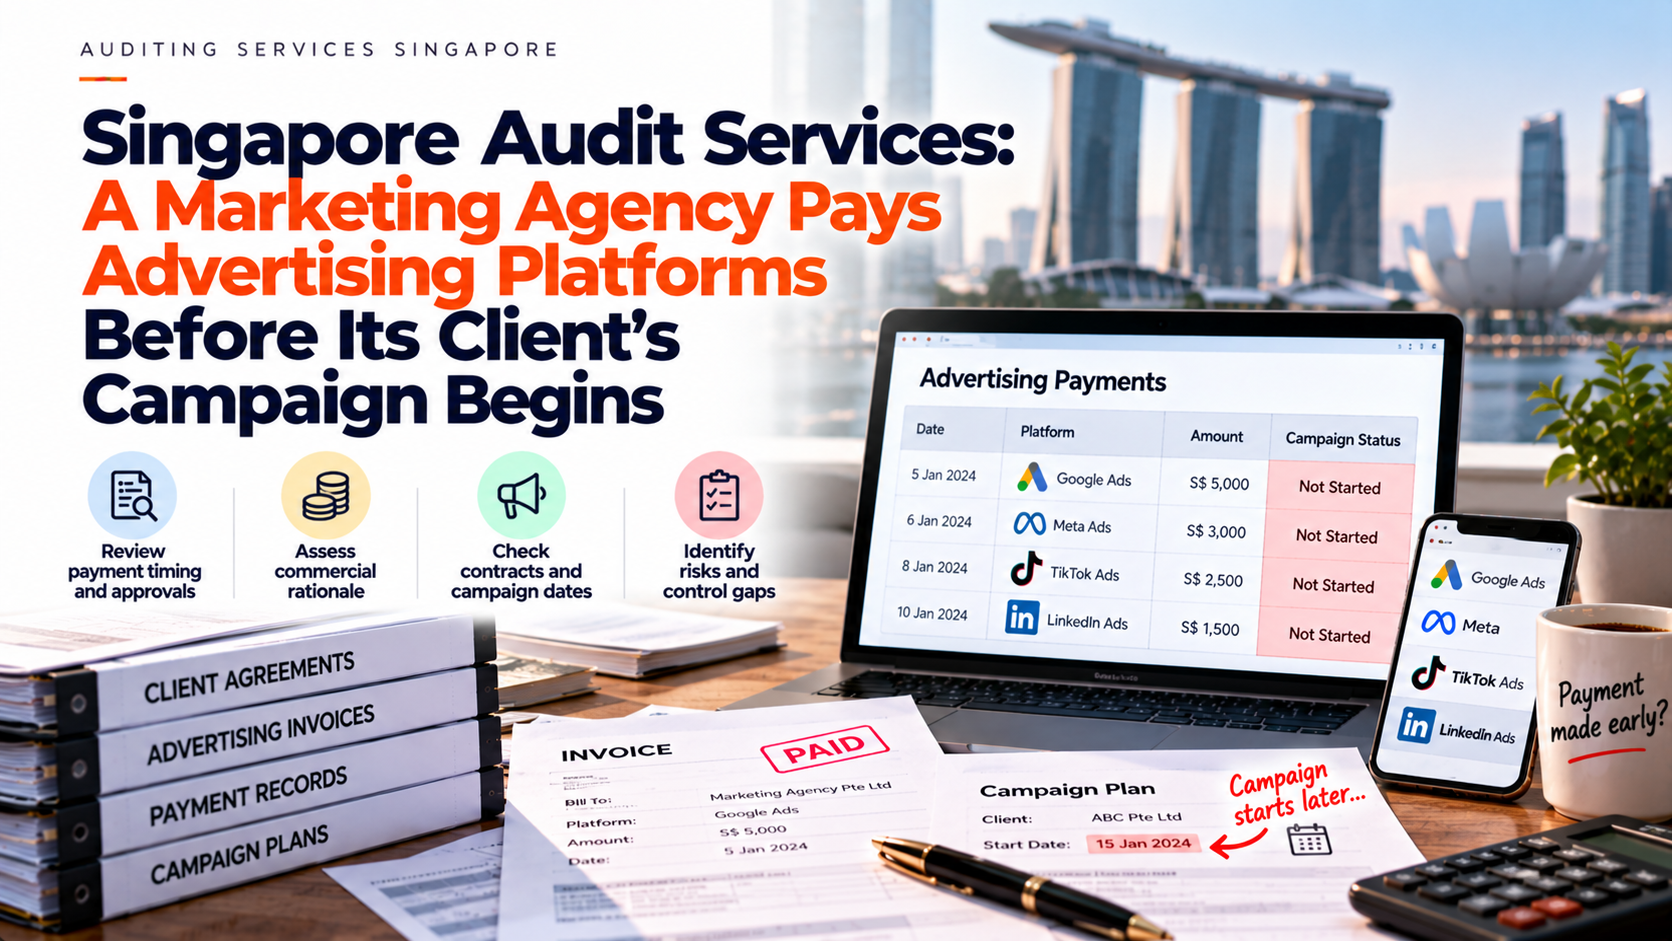
A marketing agency transfers money to an advertising platform in December for a campaign scheduled to begin in January. The payment appears on the company’s bank statement, and finance records it against the client’s project. When the year-end accounts are prepared, the full amount has been charged as advertising expenditure.
The campaign has not started, however, and the platform still shows an unused balance. The agency has paid cash, but it needs to establish what it received in exchange and whether the amount recorded reflects the position at year-end.
For businesses considering Singapore audit services, this distinction is important when preparing financial statements. Gekonnt PAC provides financial statement audit services. For a marketing agency, clear records connecting platform payments, advertising delivered and client arrangements help support the accounting assessment before the audit begins.
A Platform Payment Does Not Establish When Advertising Was Delivered
Advertising platforms can collect money before, during or after campaign activity, depending on the account and billing arrangement. The payment date therefore does not necessarily establish when the advertising service was received.
A bank transfer may fund future advertising, settle charges already incurred or cover a combination of both. Finance needs the platform’s billing and activity records to distinguish these possibilities.
Where the agency controls a right to future advertising services, an unused payment may represent a prepayment rather than an immediate expense. The treatment depends on the arrangement, including who holds the relevant rights and whether the balance remains usable.
Recording every platform payment directly as expenditure can distort monthly results. It may overstate costs in the funding month and understate them when the advertising actually runs. The review should connect the accounting entry with the service received, rather than rely on cash movement alone.
Establish Who Holds the Platform Account and Rights
An agency may operate advertising through its own account, manage an account owned by the client or use a combination of arrangements. These differences affect the assessment of what the agency controls and what it owes to the client.
Identify the legal account holder, the contracting party and the party entitled to unused funds or future advertising. Administrative access does not necessarily establish ownership of the balance.
For example, an agency might have permission to manage campaigns in a client’s account while paying certain charges on the client’s behalf. That arrangement needs to be distinguished from purchasing advertising in the agency’s own name as part of a service it supplies.
Retain the platform terms and client agreement together. Finance should be able to explain the rights involved without relying solely on the account manager’s understanding of how the relationship usually works.
Reconcile Funding With Advertising Activity
Prepare a reconciliation showing the opening balance, payments, advertising charges, refunds and other adjustments. The resulting amount should agree with the relevant platform records and the company’s ledger, with differences explained.
This is more useful than treating a screenshot of the current balance as sufficient year-end support. A live dashboard may include transactions after the reporting date or combine several categories of balance.
Consider a hypothetical agency that pays S$60,000 into its own advertising account before year-end. Assume it controls the right to future advertising, the balance remains usable and taxes and other adjustments are excluded. Platform records show S$15,000 of advertising delivered before year-end and S$45,000 remaining unused.
The accounting review should distinguish those amounts. The S$60,000 payment alone does not demonstrate that the agency received S$60,000 of advertising services during the reporting period. The client-side revenue treatment remains a separate assessment.
Check the Reporting Period Used by the Platform
Platform activity reports and accounting records may use different dates or time zones. A report downloaded in January can also include revised charges, refunds or adjustments relating to earlier activity.
Finance should confirm the reporting period, account identifiers and settings used in the export. Where billing and performance reports differ, establish whether the difference reflects timing, tax, credits or another identifiable cause.
Campaign performance figures are not always the same as final billing figures. An operational report used to monitor clicks or impressions should not automatically replace the documents supporting the financial transaction.
Keep the relevant exports and explanations in the year-end file. This allows the agency to reproduce its reconciliation later, rather than trying to reconstruct an earlier position from a dashboard that has continued changing.
Separate Agency Fees From Client Advertising Budgets
A client may pay the agency one combined amount covering advertising expenditure, campaign management and creative work. That payment still needs to be understood in terms of the promises made to the client.
Determine what the agreement says about unused advertising funds, cancellations and additional spending. Does the agency retain unused amounts, return them or carry them forward? Is the management fee separately identified, and what work earns that fee?
An advance receipt from the client does not automatically establish that all related revenue has been earned. Equally, the timing of the platform payment does not determine when the agency has fulfilled its own obligations.
The records should distinguish client receipts, platform funding, advertising activity and fees. Combining them into one project balance can obscure both the agency’s financial position and its responsibilities to the client.
Assess Gross or Net Revenue From the Actual Arrangement
The agency’s role in providing advertising also matters. Under IFRS 15, an entity assesses whether it controls the specified goods or services before they are transferred to the customer, or whether its promise is to arrange for another party to provide them.
This principal-versus-agent assessment affects gross or net revenue presentation. It cannot be resolved simply by asking who made the platform payment or whose name appears on the client invoice.
The agency should identify the service promised and evaluate the relevant contractual facts. It may provide its own campaign management services while having a different role in relation to media purchases.
Document the conclusion separately from the platform balance reconciliation. The reconciliation establishes the movement of funds and charges. It does not, by itself, establish the correct revenue presentation for the client arrangement.
Avoid Treating Every Dashboard Credit as the Same Asset
An advertising account may display paid funds, promotional credits, billing adjustments or other incentives. These categories can have different conditions and should not automatically be combined at face value.
A promotional credit may have an expiry date or usage restrictions and may not represent cash the agency can withdraw. A billing adjustment may relate to an earlier charge rather than a new payment.
Separate the categories and retain the terms that apply to each. The company should be able to explain which amounts originated from its own payments and what benefit or refund right each balance represents.
Refundability also needs verification. For example, Google Ads publishes refund eligibility requirements, but those terms should not be assumed to apply to every platform or account. Check the specific arrangement before describing an unused balance as readily recoverable cash.
Review Delayed and Cancelled Campaigns
An unused balance may remain fully usable for a campaign that has simply moved to a later date. A cancelled client engagement raises additional questions about whether the agency can use the funds elsewhere or must return money to the client.
Obtain the latest campaign status and supporting correspondence. Confirm whether the advertising account has restrictions, whether the balance can be transferred and whether a refund has been requested or approved.
A balance should not remain unchanged merely because the platform continues displaying it. Management needs to assess whether the rights represented by the amount remain available and supportable.
If the agency owes a refund to the client but cannot immediately recover the platform funds, that creates a cash planning issue as well as an accounting question. The two positions should be assessed separately rather than assuming one automatically cancels the other.
Preserve Client-Level Detail Within Shared Accounts
Some agencies use shared billing arrangements across multiple campaigns or clients. A total platform balance can then be correct while the allocation between projects is incomplete.
Maintain a schedule connecting payments and advertising charges to the relevant client or campaign. Where the platform does not provide a direct allocation, document the method used and reconcile the total.
Without that detail, one campaign’s activity may consume funds management believes are reserved for another. Client profitability reports can also become misleading if advertising costs are assigned to the wrong project.
Gekonnt’s accounting and bookkeeping services are relevant to maintaining the supporting records used in financial reporting. Operational teams still need to supply accurate campaign information so that finance can connect the billing data with the correct client arrangement.
Keep Currency and Payment Differences Explainable
An agency may pay a platform in one currency while maintaining its accounts or billing the client in another. Card processing fees and currency conversion can also create differences between the bank entry and the platform amount.
Record the original payment currency and distinguish the platform funding from separately identifiable fees. The relevant exchange rates and accounting treatment should be assessed under the applicable requirements.
Do not force the platform balance to agree with the bank payment by adjusting advertising expenditure without explanation. The difference may have a legitimate cause that belongs elsewhere in the records.
The same discipline applies when refunds arrive. Match the receipt to the original account and transaction, then explain any difference arising from fees, currency or partial recovery. A clear trail is more useful than an unexplained net figure.
Prepare Evidence for the Financial Statement Audit
For a financial statement audit, management should be able to explain material advertising balances and the basis of their accounting treatment. Relevant evidence can include platform agreements, billing exports, payment records, campaign activity and client contracts.
The audit team may examine whether the records support the balance at the reporting date, whether services have already been received and whether the amount remains recoverable. Procedures depend on the risks and circumstances of the engagement.
A platform confirmation or statement may support one aspect of the balance without resolving every issue. It may show available funds while leaving questions about ownership, restrictions or client obligations.
For agencies arranging Singapore audit services, a concise assessment alongside the documents can make discussions more focused. Explain the amount, the rights involved, the reconciliation and any unresolved matters. Management remains responsible for its accounting conclusions and supporting evidence.
Review Subsequent Use Without Losing the Year-End Position
Advertising delivered after year-end can help demonstrate what happened to an unused balance. Refunds, account restrictions and changes in client instructions can also provide information relevant to management’s review.
Keep those developments separate from the original reporting-date reconciliation. A January campaign charge should not be inserted into December activity merely to make the remaining balance smaller.
Where later information affects the assessment of conditions at year-end, finance should evaluate the applicable subsequent-event requirements. The timing and nature of the development matter.
A dated record of subsequent usage and receipts helps management explain the outcome. It also prevents an old prepayment from remaining in the ledger after the platform has already applied it to advertising.
Build a Monthly Review Around Funding, Usage and Obligations
The issue is easier to manage when platform balances are reviewed monthly rather than only during audit preparation. Reconcile payments and activity, confirm campaign status and investigate old unused amounts.
The review should include both finance and the people managing the campaigns. Finance can identify an unexplained balance, while the account manager can clarify whether work is delayed, cancelled or scheduled to begin.
Gekonnt PAC provides financial statement audit services alongside accounting and bookkeeping services. Marketing agencies can discuss their reporting arrangements and the records needed to explain platform funding and client transactions.
For businesses seeking Singapore audit services, the practical starting point is a clear distinction between money paid, advertising received and services owed to clients. When those elements are recorded separately and reconciled, management has a stronger basis for explaining its costs, balances and reported performance.