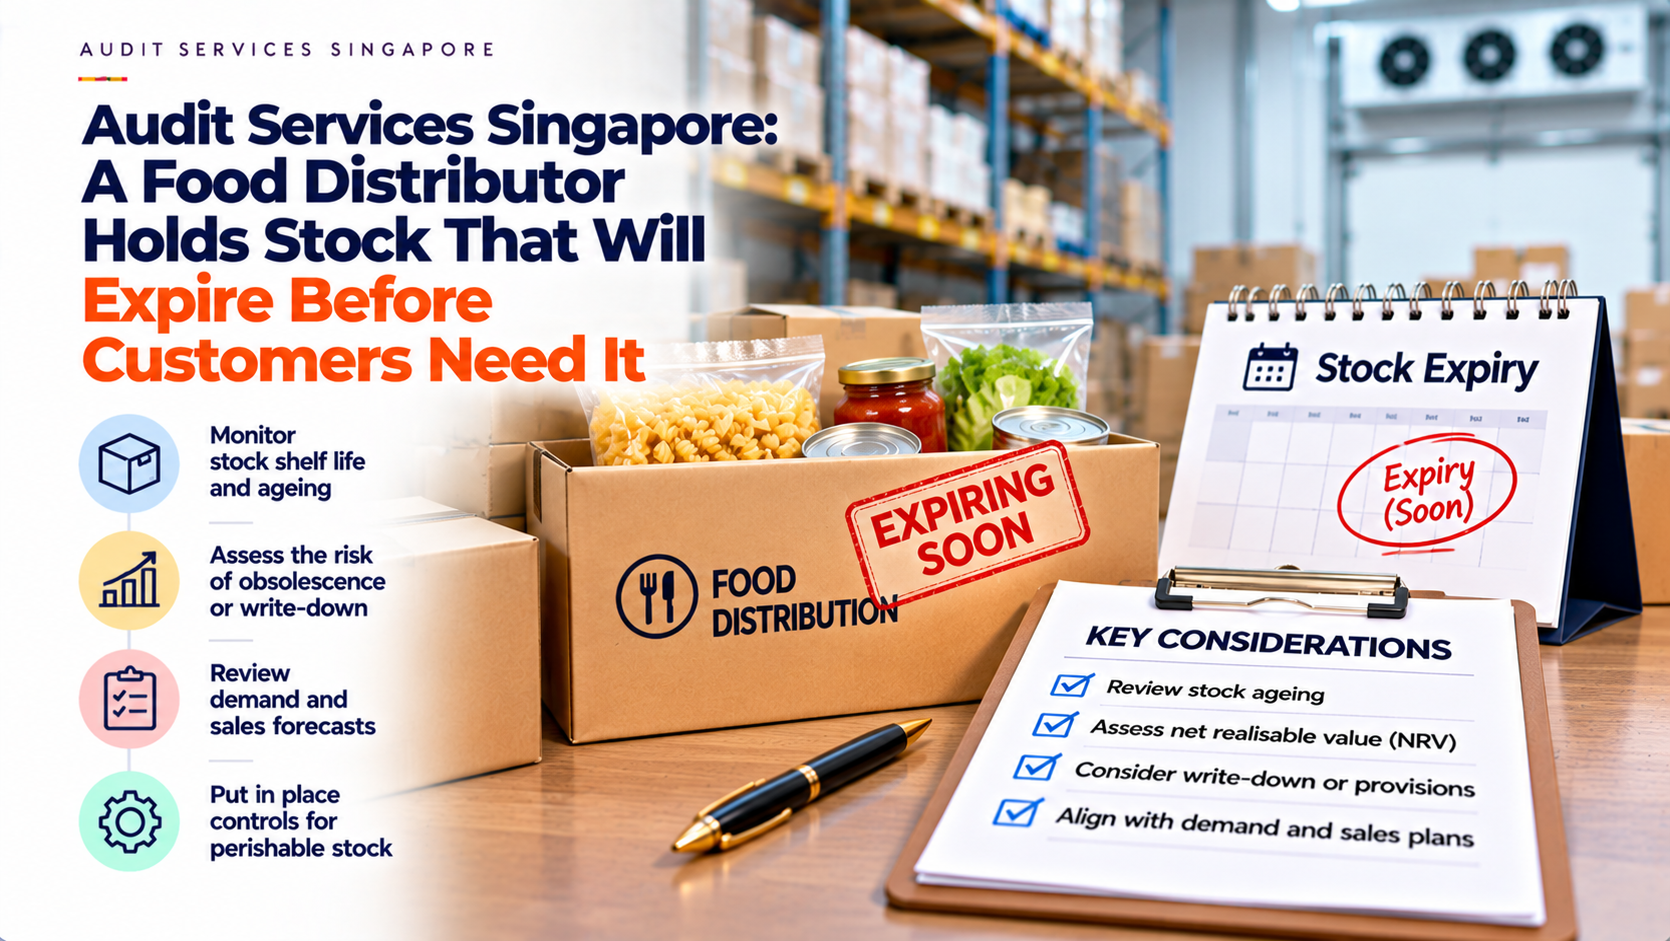
The warehouse contains enough stock to cover several months of sales. Purchasing secured a favourable price, the goods arrived in good condition and the inventory system shows their full cost. On paper, the distributor appears well supplied for the next trading period.
However, the expiry dates tell a different story. Several batches have only a short selling window remaining, and major customers require a minimum shelf life when goods reach their premises. By the time those customers place their next orders, some products may no longer meet their acceptance requirements.
For a food distributor considering audit services Singapore, the issue extends beyond whether the stock physically exists. Management needs evidence that its recorded value remains recoverable. Gekonnt PAC provides financial statement audit services relevant to reviewing these estimates and the records supporting them.
Distinguish Expiry From the Last Commercial Delivery Date
The date printed on a product is not necessarily the last date on which a distributor can sell it to its usual customers. A retailer, hotel or food-service operator may require a specified remaining shelf life at delivery. Transport and receiving arrangements can shorten the available window further.
For example, a customer might require at least 90 days of remaining shelf life. A batch with 110 days remaining therefore has a much shorter commercial delivery window than its expiry date alone suggests. The distributor must also allow time for order processing and transport.
Document these requirements by customer and product where they differ. A forecast based solely on the printed date can overstate the quantity likely to be sold through normal channels. The relevant assessment needs to reflect when customers will actually accept the goods.
Prepare a Batch-Level View of the Exposure
A product-level inventory total can conceal important differences between batches. The company may hold both recently received goods and older stock approaching the end of its commercial selling window under the same product code.
Prepare a schedule showing quantities, batch references, relevant date labels, recorded costs and warehouse locations. Identify goods held by third-party logistics providers as well as stock in the company’s own premises. Reconcile the schedule with the inventory records and investigate missing or inconsistent dates.
Warehouse staff should confirm that the information agrees with the physical labels. A report built from default dates or incomplete data will not provide a reliable basis for estimating recovery. Finance needs to know which specific quantities are exposed before assessing their value.
Test Demand Against the Time Remaining
Historical sales provide useful context, but they do not establish that the same quantities will sell before the remaining window closes. Seasonal demand, customer losses, menu changes or a recent promotion may make the historical average unsuitable.
Compare the affected batches with confirmed orders and realistic demand forecasts for the relevant weeks. Distinguish customer commitments from sales targets. An annual forecast may appear sufficient while placing most expected demand after the batch becomes unacceptable to the intended buyers.
Also consider competing stock. If customers prefer newer batches, the business may sell fresh arrivals while older goods remain untouched. The forecast should explain how the affected quantities will be allocated, rather than assuming every future sale will automatically reduce the oldest stock.
Review How Stock Is Selected for Dispatch
An expiry-aware dispatch process can reduce avoidable waste, but its effectiveness depends on actual warehouse practice. Staff may select the easiest pallet to reach, follow receipt dates rather than expiry dates or reserve older batches for orders that never materialise.
Review recent dispatch records to see which batches were used. Compare the remaining shelf life of goods shipped with those left behind. Where exceptions were necessary to meet customer requirements, retain the reason.
The review should connect warehouse decisions with the sales plan. Sending newer goods may be appropriate for a customer with stricter requirements, while another customer could accept a shorter remaining shelf life. That allocation needs to be supported by real orders and acceptance terms, not an assumption that an alternative buyer will eventually appear.
Assess Inventory at a Recoverable Amount
Under IAS 2, inventories are measured at the lower of cost and net realisable value. Net realisable value reflects the estimated selling price in the ordinary course of business, less estimated completion costs and costs necessary to make the sale. Management should apply its relevant reporting framework.
Near-expiry stock may still be saleable, but at a reduced price or with additional selling costs. Other quantities may have no supportable sales route. The assessment should distinguish those outcomes rather than applying the normal selling price to the entire balance.
A write-down does not need to wait until the goods physically expire. Where available evidence shows that cost cannot be recovered, the accounting assessment should reflect that position at the reporting date. Equally, a short remaining shelf life does not automatically require every affected item to be written down to zero.
Show the Financial Effect With a Supported Calculation
Consider a hypothetical distributor holding 1,000 cartons at a recorded cost of S$30 each. The total cost is S$30,000. Its supported assessment indicates that 400 cartons can be sold through normal channels before the relevant delivery deadline.
Assume the net realisable value of those 400 cartons exceeds their S$12,000 cost. Another 300 cartons have a credible clearance route at S$22 each, with S$2 per carton of necessary selling costs. Their net realisable value is therefore S$6,000, compared with a recorded cost of S$9,000.
The remaining 300 cartons have no supportable recovery route and are assessed at zero. On these simplified assumptions, the inventory carrying amount would be S$18,000 and the write-down S$12,000. The example excludes GST and any separate disposal obligation. Its usefulness depends on evidence supporting the quantities, prices and costs assumed.
Support Clearance Plans With Commercial Evidence
A proposed discount campaign may help recover cash, but a plan alone does not establish the amount recoverable. Management should assess whether the intended buyers can accept the products within the available time and whether the proposed price is realistic.
Useful support includes written offers, confirmed clearance orders and comparable recent transactions. Identify how many units each arrangement covers. An offer for a small quantity should not automatically be extended to the whole batch.
Check the full commercial terms as well. Buyers may require additional delivery services or hold return rights that affect the expected outcome. Clearance assumptions must also remain within applicable food-safety and labelling requirements; an accounting recovery plan does not authorise an otherwise impermissible sale.
Treat Supplier Returns as a Separate Recovery Route
The distributor may expect the supplier to take back unsold goods or issue a credit. That expectation needs to be checked against the agreement, including notice periods, eligible products, condition requirements and responsibility for transport.
A supplier’s general willingness to discuss returns is different from acceptance of a specified batch. Obtain confirmation of quantities and settlement terms where possible. Track deadlines so that a potentially recoverable amount is not lost through late notification.
Avoid counting both resale proceeds and a supplier credit for the same cartons. Finance should also assess how any accepted return or claim is reflected in the accounts. The physical movement, credit documentation and recorded balance need to tell a consistent story.
Review Goods Already Delivered With Return Rights
Moving stock out of the warehouse does not necessarily eliminate the exposure. Customers may be entitled to return unsold goods or reject products that fail agreed shelf-life conditions. A large shipment near year-end therefore needs to be understood in the context of its terms.
Review the arrangements and subsequent returns with the sales team. Identify products placed with customers under sale-or-return or similar terms, and ensure finance assesses the relevant revenue and inventory consequences under the applicable framework.
The purpose is to prevent a warehouse problem from being hidden in customer balances. A shipment that is likely to come back should not be treated as a straightforward resolution merely because the dispatch report shows the quantity leaving the premises.
Prepare an Audit File That Connects the Evidence
For an engagement involving audit services Singapore, a physical count can support the existence of inventory. It does not, on its own, demonstrate that customers will buy the goods at an amount supporting their recorded value.
Prepare an assessment linking batch quantities and costs to customer requirements, demand forecasts, clearance arrangements and supplier-return evidence. Explain the assumptions and identify any significant uncertainty. Keep the underlying documents accessible so that the calculations can be followed.
Gekonnt’s financial statement audit services provide a relevant basis for discussing the evidence required. Management remains responsible for its estimates and accounting conclusions, while the auditor independently evaluates the supporting information. Preparing the assessment early helps avoid reliance on last-minute explanations.
Use Later Sales to Review Earlier Assumptions
Actual sales after the reporting date can help management assess the reasonableness of its estimates. Compare the quantities sold, realised prices and selling costs with the assumptions used for the affected batches.
However, consider the circumstances behind those later transactions. A sale under conditions that arose subsequently should not automatically be treated as evidence of the position at the earlier reporting date. Record when relevant information became available and what it indicates.
Unsuccessful clearance attempts are also useful evidence. If anticipated buyers repeatedly decline the goods or demand deeper discounts, revisit the recovery estimate. Keeping the same valuation simply because the original plan remains on file does not address changing facts.
Separate the Write-Down From Physical Disposal
Reducing an inventory balance does not remove the cartons from the warehouse. The business may continue paying for space, handling and temperature-controlled storage after the recorded value has fallen to zero.
Maintain a separate operational plan for goods requiring disposal or another permitted outcome. Identify approval responsibilities, quantities and supporting records. Ensure the physical movement is reflected in the stock system without recognising the same inventory loss twice.
Staff also need to know which goods have been quarantined or withdrawn from sale. Accounting status and product-release decisions serve different purposes, but they should be coordinated. Clear records help prevent unsuitable stock from being dispatched accidentally or written-off quantities from remaining unexplained in future counts.
Bring Expiry Exposure Into Purchasing Decisions
The valuation review should inform future purchasing. A lower unit price may be outweighed by the cost of quantities that cannot be sold within the available window. Minimum-order requirements and promotional buying should therefore be assessed against realistic demand.
Compare expected landed quantities with existing batches, customer acceptance requirements and sales timing. Include stock already ordered but not yet received. Otherwise, procurement may continue replenishing a product while finance is assessing a write-down of the same range.
Assign responsibility for acting on the results. Sales can refine demand expectations, procurement can review order quantities and warehouse teams can improve batch selection. Finance should track whether these actions reduce losses rather than treating expiry adjustments as an unavoidable annual exercise.
Connect Shelf-Life Records With Reliable Financial Reporting
A food distributor’s inventory value depends on more than the number of cartons available. Remaining shelf life, customer requirements and realistic recovery options determine whether the recorded cost remains supported.
A useful assessment brings those factors together at batch level. It distinguishes normal sales, clearance opportunities, supplier returns and quantities without a credible recovery route. That clarity supports both financial reporting and decisions about purchasing, allocation and disposal.
For distributors considering audit services Singapore, discuss significant expiry exposure with Gekonnt PAC early. Bring the batch records, customer acceptance terms and recovery calculations so that the audit information requirements are clear and management can address unresolved valuation questions before reporting deadlines.