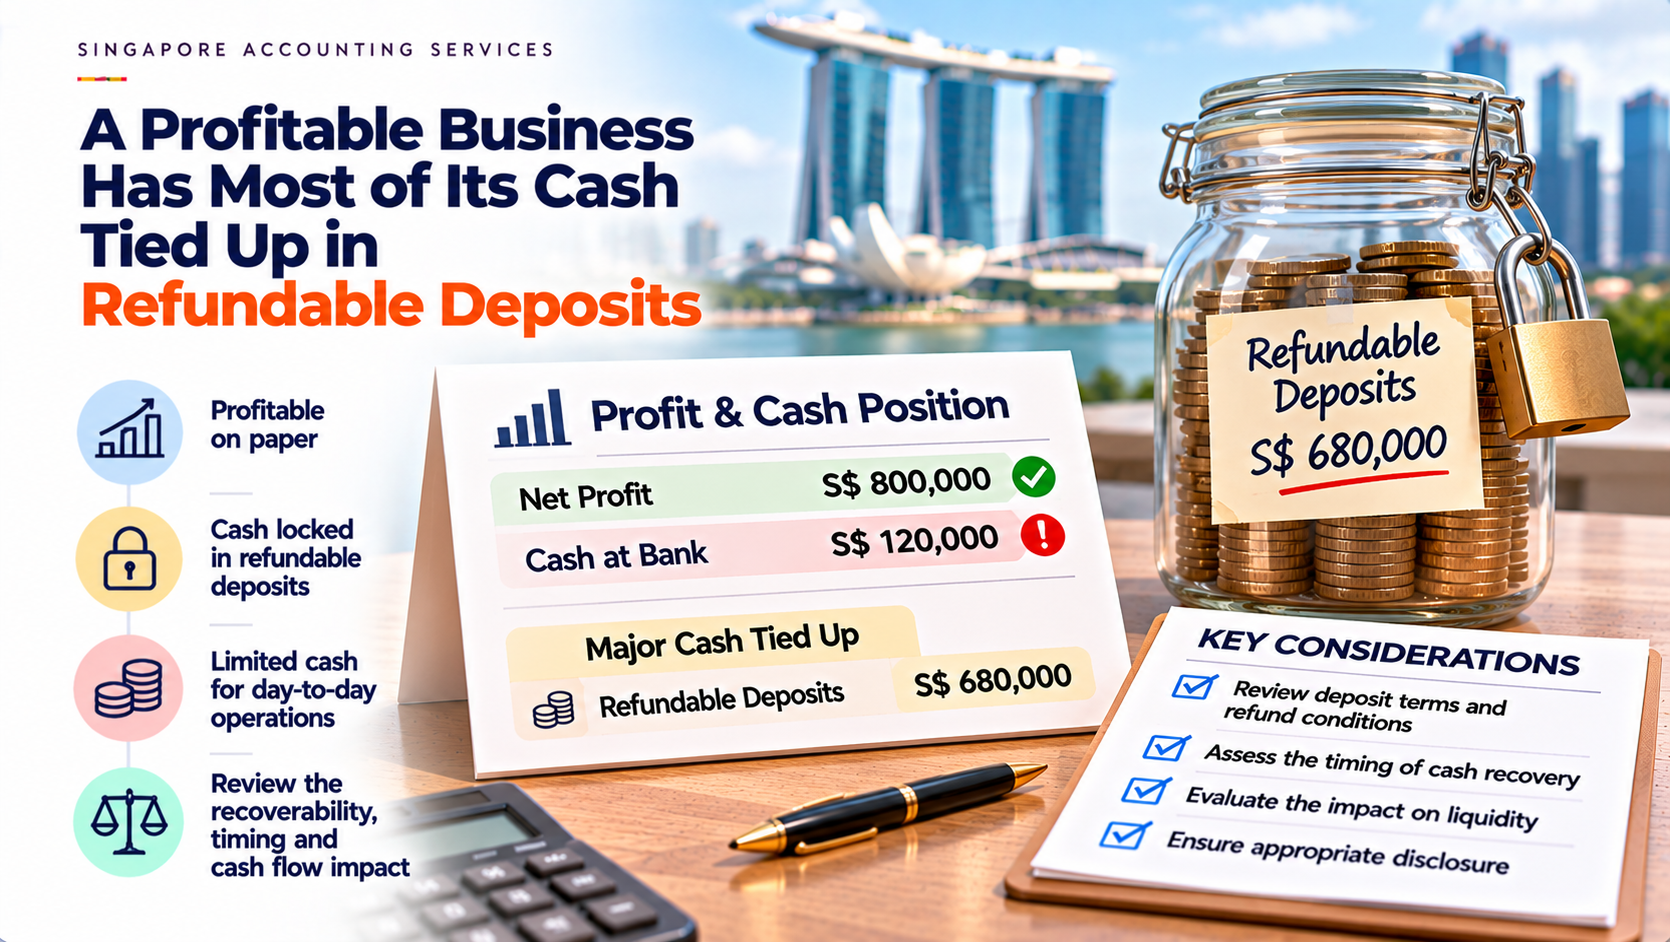
The company reports a healthy profit, but its bank balance leaves little room for unexpected payments. Several months of rent sit with landlords as security deposits. Utilities, equipment providers and commercial counterparties hold additional amounts. Each deposit is described as refundable, so management considers the money safe.
The difficulty is availability. A deposit refundable when a three-year agreement ends cannot fund next month’s payroll. Another deposit may become recoverable only after inspections, final bills or contractual conditions have been resolved. Although the amounts remain recorded as assets, the company cannot necessarily use them when cash is needed.
Gekonnt PAC provides accounting, financial analysis and advisory services relevant to understanding this difference. For management, the priority is to establish how much money is committed, when it can realistically return and what funding the business needs in the meantime.
Explain Why Profit and Available Cash Differ
A refundable deposit generally represents an asset when the company has an appropriate right to recover it. Paying the deposit therefore does not necessarily create an immediate expense equal to the cash outflow. The business can report a profit while its accessible cash falls.
This becomes particularly noticeable during expansion. Opening several outlets may require substantial deposits before the locations begin generating receipts. Those payments can consume liquidity without appearing as equivalent operating costs in the profit and loss statement.
Prepare a reconciliation explaining the difference between profit and cash movement. Identify deposits paid, deposits recovered and other significant uses of funds. Management should be able to see how profitable trading can coexist with a reduced ability to meet immediate commitments.
Identify What Each “Deposit” Actually Represents
The ledger description is only a starting point. A security deposit, an advance for future purchases and a non-refundable reservation fee create different rights. Grouping them together can conceal amounts that will never return as cash.
Review the underlying agreements and payment records. Establish whether the company can receive a refund, must apply the amount against future supplies or has paid for a service already provided. Identify any circumstances in which the amount can be forfeited or deducted.
This classification helps both reporting and forecasting. A payment that will reduce a future supplier bill should not also appear as an expected cash refund. Similarly, an amount incorrectly labelled refundable should be reviewed before management relies on it as a recoverable asset.
Build a Deposit Register With Release Conditions
A useful deposit register contains more than the counterparty and amount. It should identify the agreement, payment date, currency, responsible employee and the event that allows recovery. Include the contractual notice period and the steps needed to request release.
Different deposits may have different triggers. One may be refundable after a lease ends, another after equipment is returned and another after the final account is agreed. The date of the original payment provides little insight into those conditions.
Link each entry to supporting documents and reconcile the total to the ledger. Missing agreements should be treated as an information gap requiring follow-up. A balance carried forward for years without documentation is difficult to assess, even when the amount has never been disputed.
Distinguish Contract End Dates From Refund Dates
The end of a contract does not always coincide with receipt of the refund. Handover, inspection and final billing may occur afterwards. Management should understand these steps before inserting an expected receipt into the cash forecast.
For a premises deposit, identify whether reinstatement work or outstanding charges need to be resolved. For equipment, check return and condition requirements. Record who must confirm completion and what evidence the counterparty needs before processing repayment.
The forecast should use a supported recovery date. If the timing remains uncertain, show the uncertainty rather than choosing the contract end date for convenience. Repeatedly moving an expected refund into the following month is a sign that the underlying release process needs attention.
Measure the Immediate Funding Gap
Consider a hypothetical business with S$700,000 recorded in refundable deposits and S$180,000 of unrestricted bank cash. During the next eight weeks, it expects S$350,000 of customer receipts and S$600,000 of operating payments. None of the deposits is expected to be released within that period.
On those assumptions, the business faces a S$70,000 cash shortfall before allowing for any minimum operating buffer. The S$700,000 deposit balance does not remove that gap because the funds are unavailable during the relevant weeks.
If one S$100,000 refund is expected, its timing becomes critical. A receipt after the major payments fall due may still leave a temporary shortage. Management therefore needs a dated forecast rather than a comparison of total assets with total obligations.
Include Deposit Requirements in Expansion Decisions
A new branch, warehouse or service contract may look affordable when assessed mainly through rent and operating expenses. The initial deposits can materially increase the cash needed before the activity becomes established.
Include all required deposits in the investment and funding assessment. Consider whether existing deposits remain committed during the transition. Moving premises, for example, may require payment for the new location before the previous landlord releases the old security.
This overlap should be visible when management approves the project. A refundable payment still requires funding for as long as it remains outstanding. The fact that the money may eventually return does not reduce the amount needed to begin operating.
Assess Deductions Before Assuming Full Recovery
The amount originally paid may differ from the eventual refund. Agreements may allow deductions for damage, unpaid charges or other specified obligations. Management should investigate the facts rather than assuming either full repayment or acceptance of every proposed deduction.
Obtain a breakdown of amounts withheld and compare it with the agreement and supporting records. Distinguish agreed deductions from disputed claims. Finance should also check whether related expenses or liabilities have already been recognised to avoid counting the same cost twice.
Maintain a reconciliation from the original deposit to the expected refund. That record helps management understand the outstanding commercial issue and gives finance a basis for assessing the appropriate accounting treatment.
Review the Counterparty’s Ability to Repay
A contractual right to a refund is separate from the counterparty’s ability to pay. Delayed responses, financial difficulties or repeated unfulfilled repayment promises may affect the recovery assessment.
Where a refundable cash deposit falls within the relevant financial-instrument requirements, finance needs to consider applicable measurement and expected credit-loss requirements. IFRS 9 addresses these matters for financial assets within its scope. The assessment should reflect the actual arrangement and the company’s reporting framework.
Do not wait for a definitive failure before reviewing significant concerns. At the same time, age alone does not establish that a deposit is impaired when it remains properly held under an active agreement. The conclusion needs current evidence about the rights, timing and recovery prospects.
Keep Financial Reporting Separate From Liquidity Assumptions
An amount can be appropriately recorded as an asset and still offer no support for immediate payments. Its presentation in the financial statements should not be used as a substitute for a practical assessment of cash availability.
Review classification and measurement under the applicable framework, including the terms of material long-term, non-interest-bearing deposits. Finance should not assume every deposit’s carrying amount and presentation remain appropriate simply because the original payment was correctly entered.
Gekonnt’s accounting services include financial reporting and analysis. A discussion about these records can help management connect the reported balances with the agreements supporting them. The cash forecast should then show the expected cash flows separately, using evidence about when funds can actually be accessed.
Compare Alternatives Before Committing More Cash
Some counterparties may accept alternative security arrangements, staged deposits or a lower amount after a period of satisfactory performance. These possibilities depend on agreement and should be explored before assuming that cash is the only option.
Compare the full consequences. A bank guarantee may involve fees, collateral or use of a credit facility. It does not necessarily release an equivalent amount of freely available cash. A reduced deposit might also come with higher recurring charges or other conditions.
Management should evaluate the overall cost and funding effect rather than selecting the option with the smallest initial payment. Confirm the terms in writing and ensure the accounting records reflect the arrangement actually agreed.
Assign Responsibility for Recovering Released Deposits
A deposit can remain outstanding after the release conditions have been met because nobody owns the follow-up. Operations may consider the contract closed while finance continues carrying the balance without knowing that a refund can now be requested.
Assign a named employee to each recovery action. Record the documents submitted, counterparty response and expected settlement date. Escalate overdue items according to their amount and circumstances rather than relying on occasional reminders.
The process should continue until the bank receipt is matched and the balance resolved. If the refund is partial, explain the remaining amount and next action. Closing the operational file should not remove visibility of the financial balance.
Avoid Funding Routine Payments With Uncertain Refunds
When cash is tight, an expected deposit refund can become the assumption that makes the forecast balance. That creates exposure if release depends on an unresolved inspection, disputed deduction or administrative process outside the company’s control.
Separate confirmed receipts from conditional recoveries. Test what happens if a significant refund arrives later or is smaller than expected. Identify the funding response before the company reaches a payment deadline.
This does not mean excluding every deposit recovery from planning. It means matching the confidence placed in the receipt to the evidence available. A written repayment confirmation supports a different assumption from a general expectation that the counterparty should pay soon.
Review the Total Amount Tied Up Across the Business
Individual deposits may look modest while their combined value becomes significant. Several locations, suppliers and service arrangements can create a substantial commitment that no single department sees in full.
Report the total by purpose, counterparty and expected recovery period. Identify concentrations and amounts linked to activities the company no longer needs. Review new deposit requests alongside existing commitments so that management sees the cumulative cash effect.
Use the information to set internal approval expectations. Larger or longer commitments may require a more detailed funding assessment, while routine items can follow a simpler process. The aim is to ensure that refundable payments receive attention proportionate to the cash they absorb.
Turn Deposit Balances Into a Practical Cash Plan
A profitable business can still face liquidity pressure when substantial funds remain held by other parties. The financial question is how those deposits affect payments due now, the funding required for growth and the flexibility available if trading conditions change.
A complete register, supported recovery dates and regular review of deductions and counterparty risk make that exposure easier to understand. Management can then assess new commitments with a clearer view of the cash already tied up elsewhere.
If refundable deposits form a significant part of the company’s assets, discuss the reporting and cash-flow assessment with Gekonnt PAC. Bring the agreements, deposit schedule and recovery correspondence so that the recorded balances can be reviewed alongside the business’s upcoming funding needs.