A strong holiday booking season can make a travel agency’s finances look reassuring. Customers have paid deposits, several group departures are fully booked, and the bank balance has increased. Yet many of those customers have not travelled, hotels still require settlement, and some bookings remain subject to changes or cancellation.
For the owner, the challenge is understanding what those collections represent. How much relates to work already completed? How much supports trips still to be delivered? What would happen if a departure were cancelled after the agency had paid its suppliers? A booking report showing healthy sales does not answer all these questions.
Gekonnt provides financial statement audit services that bring independent scrutiny to financial reporting. For travel agencies exploring financial audit Singapore services, advance customer collections are an important area to prepare properly. Connecting each receipt to the booking, contractual promises and outstanding commitments helps explain the financial position behind a busy reservations calendar.
A Confirmed Booking Is Only the Starting Point
A travel agency may sell several different services under one brand. It might organise its own escorted tours, arrange hotel reservations, sell flights on behalf of airlines, or charge separately for itinerary planning. Although customers may pay through the same checkout, these activities do not necessarily have the same accounting treatment.
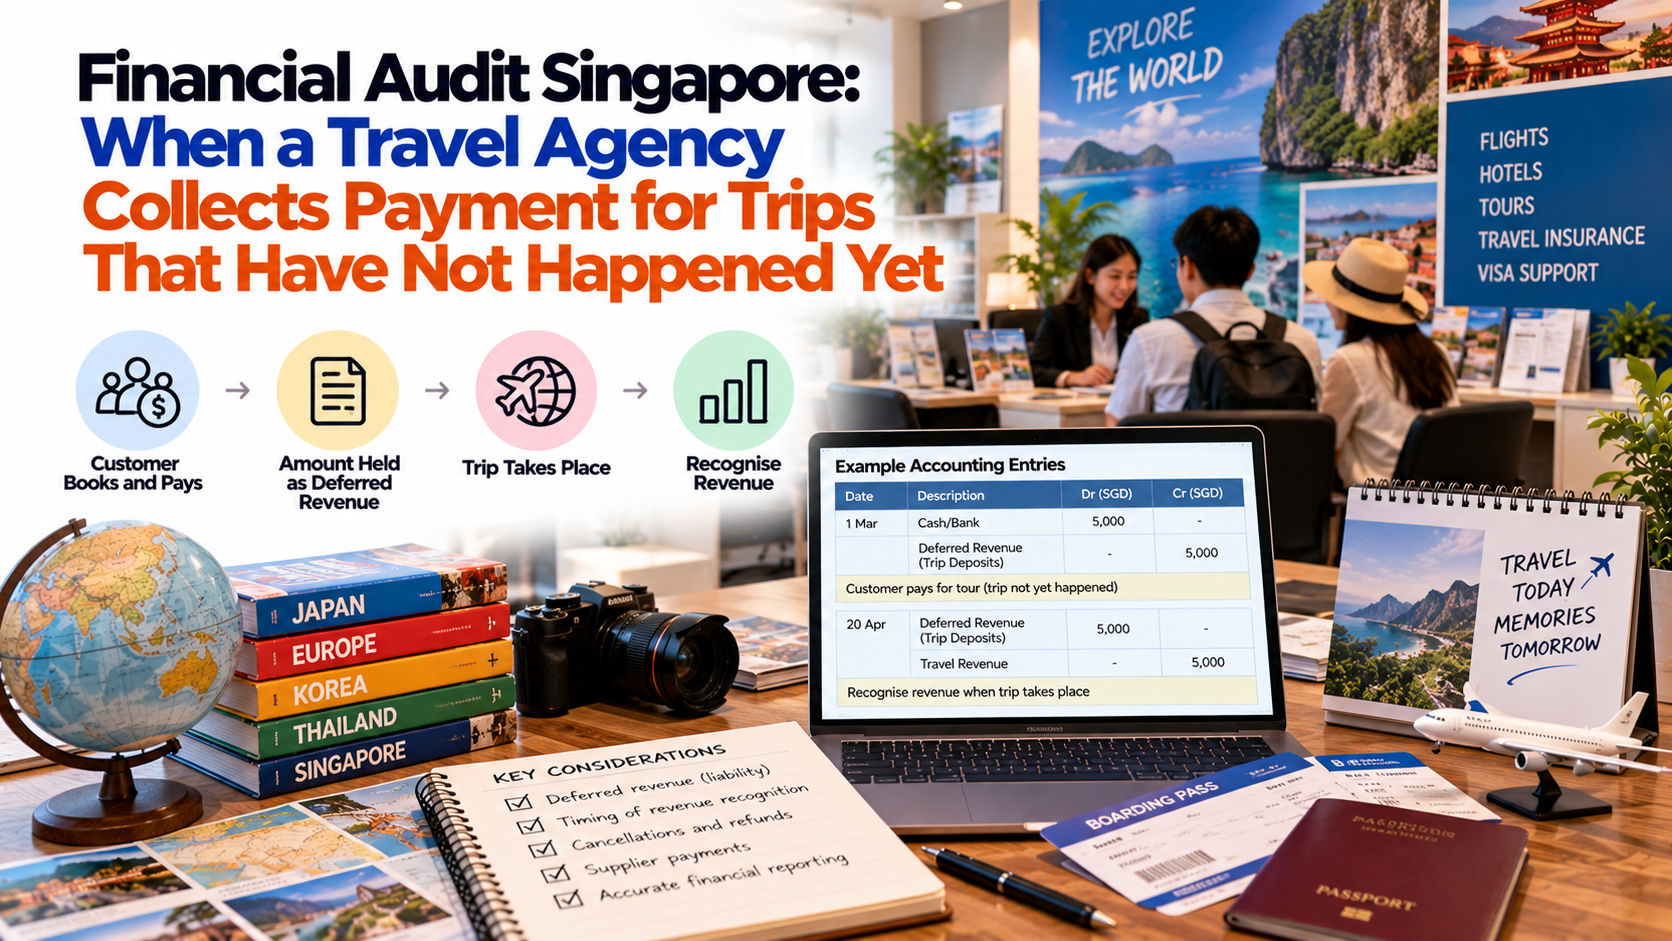
Revenue recognition follows the fulfilment of the relevant contractual promises, rather than simply the receipt of cash. Where payment precedes performance, a contract liability may arise. A separately identifiable booking service could be completed before departure, while an obligation to deliver a tour may remain outstanding. The assessment depends on what the agency has actually promised.
Management therefore needs a clear description of each product. A generic category labelled “travel sales” gives the finance team little help when a hotel-only reservation, a packaged holiday and a planning fee all appear in the same monthly export. Identifying these differences at booking stage makes subsequent review more reliable.
Build a Booking Record That Finance Can Follow
A useful booking record should connect the customer, itinerary, travel dates, agreed price and payment history. It should also identify the relevant terms, supplier commitments and any changes approved after the original booking. Finance should be able to follow the transaction without relying on the salesperson’s memory.
Consider a customer who originally books a March departure, pays a deposit in November, and moves the trip to June in January. If the reservations system shows June but the finance spreadsheet still shows March, the accounts may be updated using an outdated assumption. The receipt itself has not changed, but the underlying booking has.
Keeping a clear amendment history helps prevent this problem. The team should retain the original booking reference, show when the change was approved and explain its effect on the price, customer balance and supplier arrangements. Overwriting the old departure date without retaining that history makes later reconciliation unnecessarily difficult.
A Year-End Example: Cash Collected for a Future Tour
Consider a hypothetical agency that receives S$120,000 in December for a February group tour. It pays S$45,000 to secure accommodation and transport, leaving S$75,000 of those collections in the bank. Assume, for this example, that the agency’s promised tour service remains entirely unperformed at 31 December and that no separate service has been delivered.
Under those assumptions, the S$120,000 is an advance customer collection rather than December tour revenue. The supplier payment needs separate assessment as an advance for future services. It does not automatically justify recognising the customer collection as revenue or treating the remaining S$75,000 as profit.
For management, the next question is practical: what must that remaining cash fund? There may be further hotel payments, guide fees, attraction tickets and transport balances. A departure budget should bring those commitments together, so the owner can see how much funding the tour still requires. The bank balance alone cannot provide that view.
Supplier Deposits Need Their Own Trail
Customer receipts and supplier payments should remain traceable separately. An agency might receive money from twenty travellers but pay one deposit covering the entire group. Alternatively, one hotel payment might secure rooms for several departures. Without a supporting allocation, finance may struggle to establish which bookings a payment actually covers.
A supplier deposit schedule can record the supplier, payment date, currency, booking references, services reserved and remaining balance. It should also show cancellation deadlines and whether the supplier has acknowledged the reservation. A bank transfer confirms that money moved; it does not, by itself, explain the commercial arrangement.
Reviewing these records can uncover operational issues before departure. A payment may have been allocated to the wrong tour, a hotel may have confirmed fewer rooms than requested, or a credit from an earlier cancellation may remain unused. Each issue deserves an owner and a follow-up date, rather than being carried forward as an unexplained balance.
Customer Billings and Agency Revenue May Differ
Another question is whether the agency provides the travel service itself or arranges for another party to provide it. Under principal-versus-agent guidance, the assessment centres on control of the specified service before transfer to the customer. Handling the customer’s payment does not settle that assessment.
A principal generally recognises the relevant revenue gross, while an agent recognises its fee or commission. The conclusion can differ across services. It should be supported by the contracts and actual arrangements, rather than a blanket assumption that every amount collected is agency revenue.
For preparation purposes, keep customer terms and supplier agreements together for each main product type. Document who promises what, who deals with service failures and how prices are agreed. This gives management and the auditor a consistent starting point when discussing arrangements that otherwise look similar in the sales report.
Cancellations Require More Than a Booking Status Change
When a traveller cancels, several separate matters may need resolution. The agency must establish the customer’s entitlement, determine what suppliers will return, confirm any outstanding charges and track the actual settlement. Changing a reservation to “cancelled” does not complete those tasks.
A cancellation register can show the original payment, cancellation date, applicable terms, proposed customer settlement, supplier correspondence and approval status. It should distinguish an amount still under discussion from an agreed refund awaiting payment. This makes unresolved cases visible instead of leaving them scattered across email threads.
Non-refundable wording also needs care. An upfront fee is not automatically earned revenue merely because it is described as non-refundable. Its treatment depends on the services and remaining obligations. Likewise, a supplier’s refusal to return a deposit does not, by itself, establish what the agency may retain from the customer.
Operationally, the agency should avoid closing the file until both sides have been addressed. The customer may have received a refund while the supplier recovery remains outstanding, or a supplier credit may have arrived without being recorded against the cancelled booking. Those are different follow-up tasks and should be tracked accordingly.
Travel Credits Should Stay Visible
Some customers accept a credit for future travel instead of an immediate cash settlement. These credits can become difficult to monitor when they are maintained outside the booking system or transferred between customer accounts without a clear record. A later reservation may then use a credit that finance cannot readily trace.
Maintain a credit register showing the originating booking, amount, issue date, conditions, redemptions and remaining balance. Where a credit has a stated expiry date, keep the underlying terms available and flag the balance for accounting review. Avoid automatically moving old credits into income simply because the spreadsheet labels them “expired”.
The register also helps customer service. Staff can answer questions consistently, identify partial redemptions and prevent the same credit being applied twice. A monthly comparison between the credit register and accounting records is more manageable than reconstructing several years of movements immediately before an audit.
Prepare for Financial Audit Singapore Reviews With Booking-Level Evidence
A year-end schedule should explain the closing balances through the bookings that make them up. Useful categories include future departures, completed services awaiting final reconciliation, cancellations awaiting settlement and unused customer credits. Each category needs enough detail to explain its status.
Reconcile the total to the ledger and investigate differences. Common operational explanations might include duplicate imports, receipts awaiting allocation, refunds recorded in only one system or manual journals posted without updating the booking schedule. The objective is to resolve the difference and document the reason, rather than insert an unexplained balancing figure.
Gekonnt’s financial statement audit offering is relevant to this need for supported reporting. Management remains responsible for the records and accounting judgements; the audit provides independent examination. Clear schedules and accessible agreements give that examination a stronger evidence base and make discussions about unusual transactions more focused.
Review Activity Around the Reporting Date
Bookings immediately before and after year-end deserve a deliberate review. The team should identify trips spanning the reporting date, late amendments and services whose completion is not obvious from a departure calendar. A single system date may not capture everything needed to determine the appropriate reporting period.
It is useful to retain dated evidence of relevant activity, such as supplier confirmations, itinerary changes and service completion records. Where finance reaches a judgement, a short explanation should identify the facts considered and the supporting documents. This is especially helpful when the person handling the booking changes before the audit begins.
Subsequent events can also clarify unresolved year-end items. For example, a January settlement may provide additional information about a cancellation already being discussed in December. Finance should bring that information into the review process rather than assuming every later transaction belongs exclusively to the new reporting period.
Turn Advance Collections Into a Forward Cash View
Accurate reporting and cash planning answer related but different questions. Even when customer advances are recorded correctly, management still needs to know whether available funds will cover upcoming commitments. A departure-by-departure forecast can connect expected customer instalments with supplier payment deadlines.
Include the dates on which payments become due, rather than showing only a total expected tour margin. A profitable departure may require substantial supplier payments before the final customer instalments arrive. That timing gap matters when several tours are being prepared simultaneously.
Management can also model a delayed departure, slower customer collections or a group cancellation. The purpose is to identify pressure points early enough to respond. An agency that sees a funding gap several weeks ahead has more room to adjust payment arrangements than one that discovers it when a supplier demands settlement.
Give Each Outstanding Item a Responsible Person
Good records become more useful when responsibility is clear. Reservations staff can maintain booking status and amendments, finance can reconcile balances, and an authorised manager can review exceptions and approve settlements. The same unresolved item should not move between departments indefinitely.
A short monthly review can focus on unmatched receipts, old supplier advances, pending refunds and bookings with incomplete documentation. Assign a responsible person and target date to each material exception. At the next review, check what changed and whether supporting records were updated.
This approach also reduces dependence on individual employees. When a consultant is absent or leaves the business, another team member should be able to understand the booking and its outstanding financial matters. A well-maintained record supports continuity as well as year-end preparation.
Bring the Booking Story Into the Financial Statements
Advance payments are a normal part of travel operations, but their meaning changes as bookings progress. Money collected for a future departure, an earned arrangement fee and a refund awaiting payment should each be supported by a clear explanation. Combining them into one sales total hides information that management needs.
For agencies seeking financial audit Singapore support, preparation starts with connecting those explanations to reliable records. Booking schedules, supplier agreements, payment trails and documented judgements help make the financial statements understandable and supportable.
Speak with Gekonnt about its financial statement audit services and the records needed for your agency’s circumstances. A clear view of customer advances and outstanding travel commitments gives the audit a sound starting point and helps management understand what remains to be delivered after the cash arrives.