Three Directors, Three Different Plans
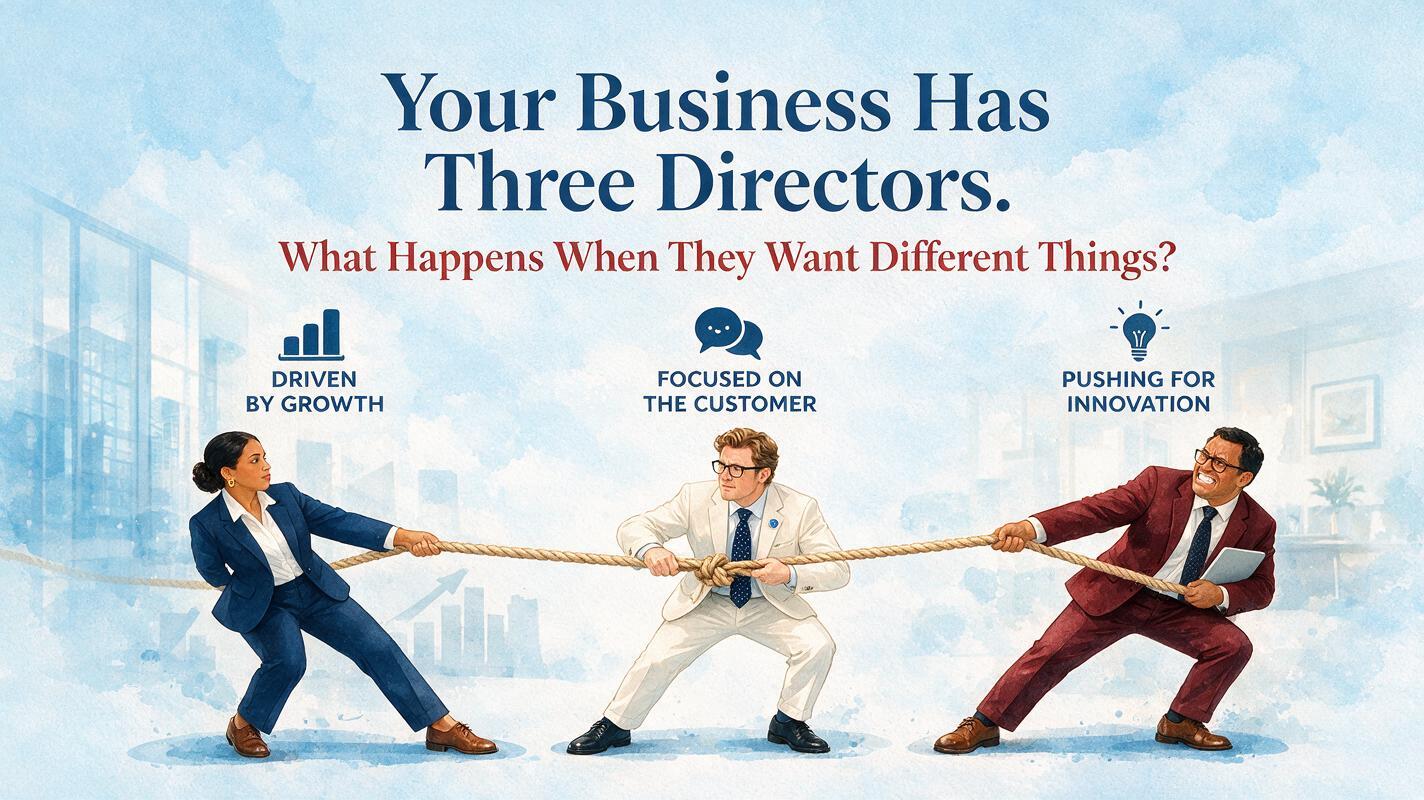
Your company has reached a point where the next decision matters. Revenue has grown, the business has built a reliable customer base, and there is money in the bank. One director wants to open a second location. Another wants to invest in technology and strengthen the existing operation. The third believes the company should preserve cash because customers are taking longer to pay. Each person can explain their position convincingly. Each believes they are protecting the business. Yet after several meetings, nothing has been decided. Employees are waiting for instructions, a potential landlord wants an answer, and the finance team has prepared three different forecasts. What happens when the people responsible for leading the same company want it to move in different directions?
Different Opinions Can Improve a Business Decision
Disagreement between directors does not automatically mean the business has a leadership problem. A company can benefit from having people who notice different opportunities and risks. A director responsible for sales may recognise demand that others have not seen. Someone overseeing operations may understand why the existing team cannot absorb another expansion. A director reviewing finances may identify cash pressure before it becomes visible elsewhere. Bringing those perspectives together can produce a stronger decision. The difficulty begins when directors stop examining the proposal and start defending their positions. Once every question feels like criticism and every concession feels like defeat, the discussion becomes less useful. A healthy board needs enough disagreement to test ideas and enough structure to reach a decision.
Find Out What Each Director Is Actually Trying to Achieve
Before debating which proposal should win, directors should explain the outcome they want. Opening another location might be about capturing demand, reducing dependence on one market, or proving that the business model can expand. Investing in technology might be about reducing errors, improving customer service, or handling more work without immediately hiring additional employees. Preserving cash might reflect concerns about uncertain collections rather than opposition to growth. These are different objectives, and they deserve to be discussed openly. Asking each director to complete the sentence “This proposal matters because…” can make the underlying issue clearer. Sometimes the directors agree on the destination but disagree about the order of investment. That is a more manageable problem than assuming they have incompatible ambitions.
Agree on the Question Before Comparing the Answers
A meeting becomes difficult when three directors are answering three different questions. One is asking how to increase revenue next year. Another is asking how to improve profitability over three years. The third is asking whether the company can meet its obligations over the next six months. All three questions matter, but they cannot be treated as interchangeable. Management should define the decision clearly before discussing the preferred outcome. For example, the question could be: “Should the company commit S$400,000 to a second location this year while maintaining sufficient cash for existing operations?” That wording identifies the proposed commitment, the timing, and an important constraint. It gives the discussion a common starting point and helps expose information that is still missing.
Put the Same Financial Information in Front of Everyone
Directors cannot have a productive discussion if they are working from different versions of the business. One may quote last quarter’s profit, another may refer to yesterday’s bank balance, and a third may rely on the sales team’s forecast. Those figures describe different things. Before a significant decision, finance should prepare a consistent set of information showing recent performance, current cash, outstanding customer balances, upcoming payments, and existing commitments. The figures should cover the same reporting periods, and forecasts should identify their assumptions. If there are unresolved accounting issues or incomplete records, those limitations should be visible. Reliable information will not remove differences in judgement, but it can prevent an argument caused by directors unknowingly comparing different facts.
A Healthy Bank Balance Does Not Settle the Argument
Consider a simplified example. The company has S$900,000 in the bank, and the proposed expansion requires S$400,000 upfront. One director sees a project the business can afford. Another points out that the company also expects S$350,000 of existing payments over the next three months and wants to retain a S$250,000 operating buffer. Looking only at those amounts, the expansion, payments, and buffer total S$1 million, exceeding current cash by S$100,000 before considering future receipts. This does not establish that expansion is unaffordable. Customers may pay enough during that period to support it. It does show why the timing and reliability of those receipts matter. The useful discussion concerns the cash forecast and its assumptions, rather than whether S$900,000 sounds like a comfortable balance.
Compare Proposals Using the Same Measures
Different proposals should face comparable scrutiny. If the director supporting expansion must provide detailed cost estimates, the director supporting technology investment should also explain implementation costs, expected benefits, and likely disruption. Similarly, keeping cash should be assessed against the opportunities that may be delayed or lost. A practical comparison can consider the initial commitment, ongoing costs, cash timing, staff requirements, expected benefits, and consequences if the proposal performs poorly. Some benefits will be difficult to quantify, but directors should still describe how they expect to recognise success. Applying consistent questions makes the discussion fairer. It also reduces the risk that the most enthusiastic presentation receives approval while a less confidently presented alternative offers better value.
Test What Happens When the Forecast Is Wrong
A forecast can appear convincing because its assumptions fit together neatly. Real business conditions rarely follow that pattern exactly. The new location may open two months late. Recruitment may cost more than expected. Customers may take longer to pay, or the technology project may require additional training. Directors should therefore examine more than the preferred forecast. A downside scenario can show how the proposal affects the company if revenue develops slowly or costs increase. The purpose is to understand the company’s ability to absorb disappointment. A director who appears overly cautious may become more comfortable once the downside is manageable. Equally, a director supporting expansion may revise the plan after seeing how quickly several modest setbacks could reduce available cash.
Recognise That Directors May Be Using Different Time Horizons
A disagreement can persist because each person measures success over a different period. One director wants to build a business that can expand significantly over the next decade. Another expects to reduce their involvement within three years. A third wants more predictable income because their personal circumstances have changed. Where directors are also shareholders, these preferences can influence discussions about investment and distributions. They should be acknowledged without allowing personal preferences to automatically determine the company’s direction. ACRA identifies acting in the company’s best interests as a key duty of directors. Making different expectations visible helps the board examine proposals more honestly and recognise when a separate ownership discussion is needed. ACRA’s guidance on company directors.
Separate Ownership Expectations From Management Decisions
In a smaller company, the same person may be a shareholder, director, and employee. That overlap can make conversations confusing. Someone may discuss their salary, expected shareholder returns, and preferred business strategy in the same meeting as though they are a single issue. Management should identify which capacity is relevant to each decision and what approval process applies. A discussion about remuneration is different from one about business investment, even if both affect cash. Likewise, a shareholder’s desire to receive money from the company does not by itself establish that a distribution should be made. Keeping these subjects distinct makes the financial consequences easier to assess and reduces the chance that a business proposal becomes a substitute for an unresolved conversation about ownership or compensation.
Do Not Assume Two Votes Automatically Resolve Everything
With three directors, it may seem that every disagreement can be settled by a simple two-to-one vote. Before relying on that assumption, the company should check the rules that govern the particular decision. Its constitution, any relevant shareholder agreement, and applicable requirements may affect authority, meeting procedures, or approvals. Some matters may also need to be considered at shareholder level. The practical step is to establish the correct process before the disagreement becomes urgent. Directors can ask the company secretary to help identify the relevant documents and obtain legal advice where interpretation is needed. Understanding the process early prevents a situation in which a commercial decision is announced and its validity is challenged afterwards.
Keep Employees Out of Competing Instructions
Director disagreements become operational problems when employees receive conflicting directions. The sales team may be told to prepare for expansion while finance is instructed to freeze spending. An operations manager may recruit staff after speaking with one director, only to learn that another director considers recruitment premature. Employees should not have to decide which director’s instruction carries more weight. Until a decision is properly made, management should communicate what has been approved, what remains under review, and who can authorise further action. After approval, the company should issue one clear implementation direction. This protects employees from becoming intermediaries in a board dispute and helps prevent commitments being made before the company has agreed to them.
Use Smaller Commitments When the Main Uncertainty Can Be Tested
Some disagreements can be resolved through a limited trial. If directors are uncertain whether another location will attract enough customers, a smaller market test may provide useful evidence before the company commits to a long lease. If the issue concerns technology, testing one process may reveal implementation demands before a wider rollout. A trial needs a defined budget, timeframe, responsible person, and assessment method. Directors should also agree on what results would justify expansion, revision, or stopping. Otherwise, the trial may continue indefinitely or become a full investment without another meaningful decision. Smaller commitments are most useful when they answer a specific question that is preventing directors from agreeing.
Record the Decision and the Conditions Attached to It
A verbal agreement can sound clear during a meeting and become surprisingly uncertain a month later. One director remembers approving the expansion. Another remembers approving it only if financing was confirmed. The third believes approval covered negotiations rather than signing a lease. Proper records should explain what was decided, any conditions, the authority given, and the next steps. Material concerns and unresolved matters should also be captured appropriately. The record does not need to reproduce every sentence spoken, but it should allow someone to understand the decision without relying on competing memories. Clear documentation is especially helpful when implementation involves several people or when the company needs to revisit the assumptions behind an earlier approval.
Give Each Approved Decision an Owner and a Review Date
Agreement is only the beginning of implementation. Once directors approve a course of action, someone needs responsibility for carrying it out and reporting progress. The company should identify who controls the budget, who can approve changes, and which developments must return to the board. A review date also matters. For an expansion project, directors might review spending, opening readiness, customer demand, and cash forecasts at agreed stages. This allows concerns to be addressed through evidence rather than repeated arguments about the original decision. Directors who opposed the proposal can still ask legitimate questions and examine new information. A clear review process gives those questions a constructive place and helps management respond consistently.
Recognise When the Disagreement Is Really About Trust
Sometimes additional forecasts and meetings do not help because the underlying issue is a breakdown in trust. Directors may doubt whether information is complete, believe commitments were made without authority, or feel that previous agreements were ignored. Repeatedly changing the financial model will not resolve those concerns. The company needs to identify the specific conduct or information gap causing the problem. That may involve reviewing access to records, clarifying delegated authority, or obtaining an independent assessment of disputed figures. Where the disagreement concerns legal rights, alleged misconduct, or a persistent inability to make necessary decisions, legal advice or an appropriately qualified mediator may be needed. Recognising the nature of the problem helps the company seek support that can actually address it.
How Gekonnt Can Support Better-Organised Decisions
Directors remain responsible for the company’s choices, but professional support can improve the records and processes surrounding those choices. Gekonnt’s corporate secretarial services include statutory record maintenance and support with meeting agendas, notices, minutes, and resolutions. These services are relevant when a company wants clearer documentation of discussions, approvals, and follow-up actions. A business can prepare for that support by gathering its corporate documents, previous resolutions, and details of the decision under consideration. The objective is to make the approval process and its records easier to follow. Directors can discuss the appropriate scope with Gekonnt’s corporate secretarial team, while seeking separate legal advice where a dispute requires interpretation of rights or remedies.
Build a Process That Works Even When Directors Disagree
Three directors do not need identical personalities, ambitions, or views on risk to lead a company effectively. They need a shared understanding of the decision, reliable information, and a clear process for reaching and implementing an outcome. That means explaining objectives, testing assumptions, checking authority, documenting approvals, and reviewing results. When these habits are established, disagreement can reveal weaknesses in a proposal before the company commits money. Without them, even a reasonable decision can become a source of confusion. For businesses working with Gekonnt, stronger corporate records and meeting support can form part of that foundation. The aim is a company that can make considered decisions and keep operating effectively when its directors see the future differently.